The January Effect: Capitalising on Seasonal Viral Opportunities in the US Market
The start of a new calendar year brings a unique surge of optimism and fresh capital across the financial landscape. Taking advantage of the January Effect allows active investors and brands alike to harness this early surge in market activity, capitalizing on heightened consumer engagement and shifting trading volume.
As tax-loss harvesting wraps up and annual bonuses hit accounts, early-year trading patterns and viral consumer shifts create brief but lucrative windows of opportunity. Recognizing these early demand spikes enables agile market participants to spot emerging trends before the broader audience catches on.
Ready to leverage this annual momentum to drive exceptional returns? Here is how you can navigate early-year market anomalies and strategically position your brand for explosive growth in 2026.
Understanding the January Effect Phenomenon
The January Effect refers to a perceived seasonal increase in stock prices during the month of January, particularly for small-cap stocks. This anomaly has been observed in financial markets for decades, leading many investors to anticipate its recurrence.
Its origins are often attributed to year-end tax-loss harvesting, where investors sell losing stocks in December to realise capital losses for tax purposes. These same investors then re-enter the market in January, driving up prices, especially for those smaller, more volatile assets.
While not a guaranteed event, the historical data surrounding the January Effect suggests a pattern worth examining for those looking to capitalise on seasonal viral opportunities in the US market. Its time-sensitive nature makes understanding its dynamics crucial for timely investment decisions.
Historical Context and Market Anomalies
The concept of the January Effect gained prominence in the 1970s and 1980s, with academic studies providing statistical evidence of its existence. These analyses often pointed to a higher average return for stocks in January compared to other months, defying the efficient market hypothesis.
Critics argue that the effect has diminished over time due to increased investor awareness and algorithmic trading, which could arbitrage away such predictable patterns. However, proponents maintain that behavioural biases and structural market features continue to provide fertile ground for the January Effect.
Examining past market behaviour offers valuable insights, but investors must remember that historical performance does not guarantee future results.
The pursuit of seasonal viral opportunities requires a nuanced understanding of both historical trends and current market conditions, especially within the dynamic US market.
Identifying the precise factors driving the January Effect remains a subject of ongoing debate among financial economists.
Beyond tax-loss selling, other theories include institutional investors rebalancing portfolios at the start of the new year, or individuals investing year-end bonuses. These combined forces can create a surge in buying pressure.
For investors aiming to capitalise on seasonal viral opportunities, understanding these underlying mechanisms is key to formulating effective strategies. The confluence of various factors contributes to this peculiar market behaviour.
Strategies for Capitalising on the January Effect
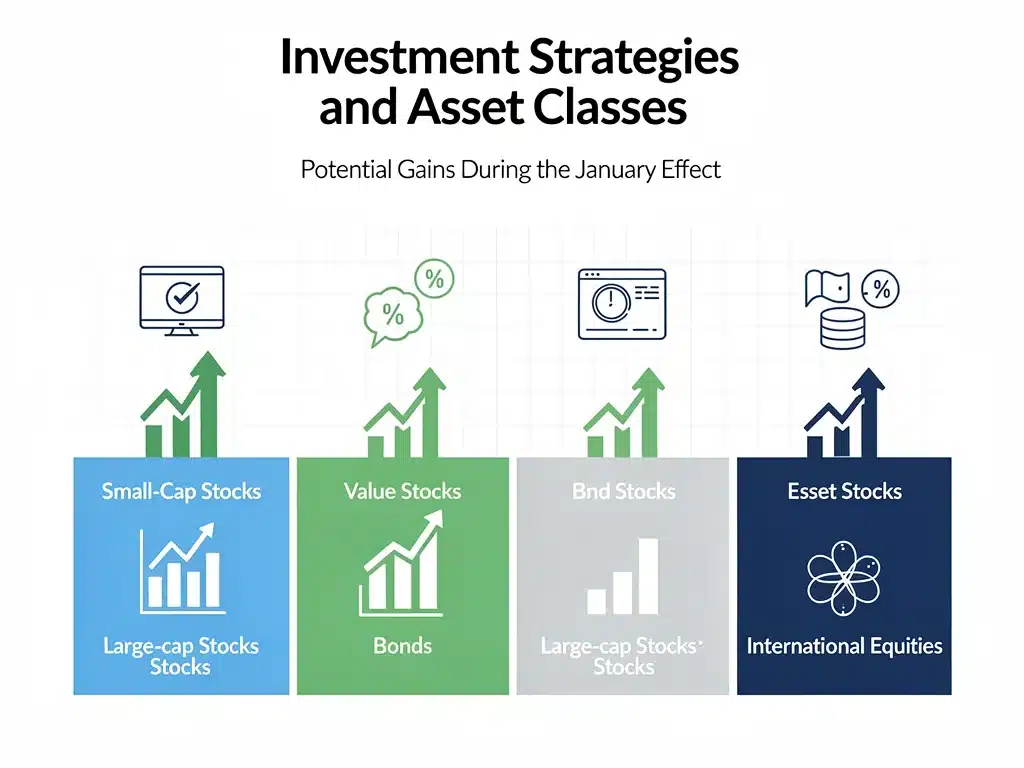
Investors seeking to leverage the January Effect typically focus on specific asset classes that have historically benefited most. Small-cap stocks are often at the forefront, given their higher volatility and potential for larger price swings.
Another common strategy involves identifying undervalued stocks that may have been sold off aggressively in December for tax purposes. These ‘bargains’ can see significant rebounds as buying activity resumes in the new year, presenting clear seasonal viral opportunities.
Timing is paramount; entering positions before the start of January and exiting towards the end of the month is the traditional approach. However, market dynamics are constantly evolving, requiring adaptability and careful research for success in the US market.
Focusing on Small-Cap Equities
- Small-cap stocks have historically shown the most pronounced January Effect.
- Their smaller market capitalisation makes them more susceptible to buying pressure.
- Researching companies with strong fundamentals but recent price declines is crucial.
The higher risk associated with small-cap investments necessitates thorough due diligence. Investors should look beyond just the seasonal factor and evaluate the company’s long-term prospects.
Considering Value and Micro-Cap Stocks
- Value stocks, often overlooked, can experience a January surge.
- Micro-cap companies, while riskier, can offer explosive growth during this period.
- Diversification within these categories helps mitigate individual stock risk.
These segments of the market can be less efficient, meaning that price discrepancies are more common and thus offer greater potential for profit during periods like the January Effect. Patience and a clear exit strategy are vital.
The Role of Tax-Loss Harvesting
Tax-loss harvesting is a primary theoretical driver behind the January Effect, influencing investor behaviour at year-end. By selling off losing investments in December, investors can offset capital gains and reduce their tax liability.
This concentrated selling pressure can depress stock prices, particularly for smaller, less liquid companies. Once the new tax year begins, investors often reinvest these funds, leading to a rebound in January, creating seasonal viral opportunities.
The timing of these tax-motivated trades makes the January Effect a time-sensitive phenomenon. Understanding this tax-driven cycle is fundamental to appreciating the seasonal patterns in the US market.
Modern Market Dynamics and the January Effect
In today’s highly interconnected and algorithm-driven markets, the traditional January Effect faces new challenges and adaptations. High-frequency trading and sophisticated algorithms can quickly exploit and potentially diminish predictable patterns.
However, behavioural finance suggests that human biases, such as optimism at the start of a new year, continue to play a role. These psychological factors can still contribute to buying enthusiasm, even if the tax-loss harvesting effect is less pronounced.
Investors must consider how these modern dynamics interact with historical patterns when seeking seasonal viral opportunities. The US market is constantly evolving, requiring a forward-looking approach to capitalising on such phenomena.
The increased transparency and accessibility of market data mean that more participants are aware of the January Effect. This widespread knowledge could, paradoxically, reduce its potency as investors front-run the anticipated price movements.
Nevertheless, the sheer volume of capital flowing into the market at the start of the year, from various sources, still provides a significant tailwind. This confluence of factors creates a unique environment for the January Effect to manifest, albeit perhaps in altered forms.
Therefore, a dynamic approach to analysing the January Effect is essential. Investors should not rely solely on past trends but also factor in current economic conditions, investor sentiment, and technological advancements affecting market efficiency.
Risks and Considerations for Investors
While the January Effect presents appealing seasonal viral opportunities, it is not without risks. Past performance is not indicative of future results, and there is no guarantee that the effect will manifest in any given year.
Market volatility, unexpected economic news, or geopolitical events can easily override any seasonal patterns. Investors must be prepared for potential losses and should not allocate an disproportionate amount of capital based solely on this anomaly.
Furthermore, transaction costs and taxes on short-term gains can erode profits, making careful planning essential. Any strategy to capitalise on the January Effect in the US market should be part of a broader, well-diversified investment portfolio.
Beyond January: Other Seasonal Anomalies
While the January Effect is perhaps the most famous, other seasonal anomalies exist in financial markets that investors might explore. These include the ‘Halloween Effect’ or ‘Sell in May and Go Away’ phenomenon, suggesting that stocks perform better from November to April.
Another observed pattern is the ‘Weekend Effect,’ where Monday returns are often lower than those on other weekdays. These anomalies, like the January Effect, are often attributed to a mix of behavioural factors and market mechanics.
Understanding these broader seasonal patterns can provide a more comprehensive view of market behaviour beyond just the January Effect. While each anomaly has its own characteristics, they collectively highlight the non-random aspects of the US market.
The Future of Seasonal Investing in the US Market
The persistence of seasonal anomalies like the January Effect in the US market continues to intrigue investors and academics alike. As markets become more sophisticated, the nature of these effects may change, but their underlying causes, whether behavioural or structural, often endure.
Future trends might see these opportunities become more subtle, requiring more advanced analytical tools and quicker execution. The role of artificial intelligence and machine learning in identifying and capitalising on these nuanced patterns is likely to grow.
For investors, staying informed and adapting strategies will be key to successfully capitalising on seasonal viral opportunities. The January Effect, even if evolving, remains a fascinating case study in market efficiency and investor psychology.
| Key Point | Brief Description |
|---|---|
| What is it | A seasonal anomaly where stock prices, especially small-caps, tend to rise in January. |
| Primary Causes | Year-end tax-loss harvesting and subsequent reinvestment in January. |
| Key Strategy | Focus on small-cap and undervalued stocks before January. |
| Main Risk | Past performance does not guarantee future results; market volatility. |
Frequently Asked Questions About the January Effect
The January Effect is a market anomaly where stock prices, particularly those of small-cap companies, tend to experience higher returns during the month of January compared to other months. It’s a widely discussed seasonal trend.
It’s primarily attributed to year-end tax-loss harvesting, where investors sell off losing stocks in December for tax benefits. They then reinvest these funds in January, especially into smaller, undervalued stocks, driving prices up.
While some argue its potency has diminished due to increased market efficiency and algorithmic trading, many believe behavioural factors and year-end portfolio adjustments still create opportunities. Its presence may be more subtle now.
Historically, small-capitalisation stocks and value stocks have shown the most significant positive returns during January. These are often the same stocks that were sold off for tax purposes in the preceding December.
The main risk is that past performance is not a guarantee of future results. Market conditions can change, and the effect might not materialise in a given year. High transaction costs and taxes on short-term gains are also considerations.
What this means
The January Effect continues to be a compelling, albeit evolving, phenomenon in the US market, offering seasonal viral opportunities for informed investors.
While its predictability has faced modern market pressures, the underlying behavioural and structural factors still provide a basis for strategic consideration.
Investors must remain vigilant, combining historical insights with current market analysis to effectively capitalise on these time-sensitive trends and integrate them into a robust portfolio strategy.